Blogs
Business Loan in India: Eligibility, Documents and How to Apply

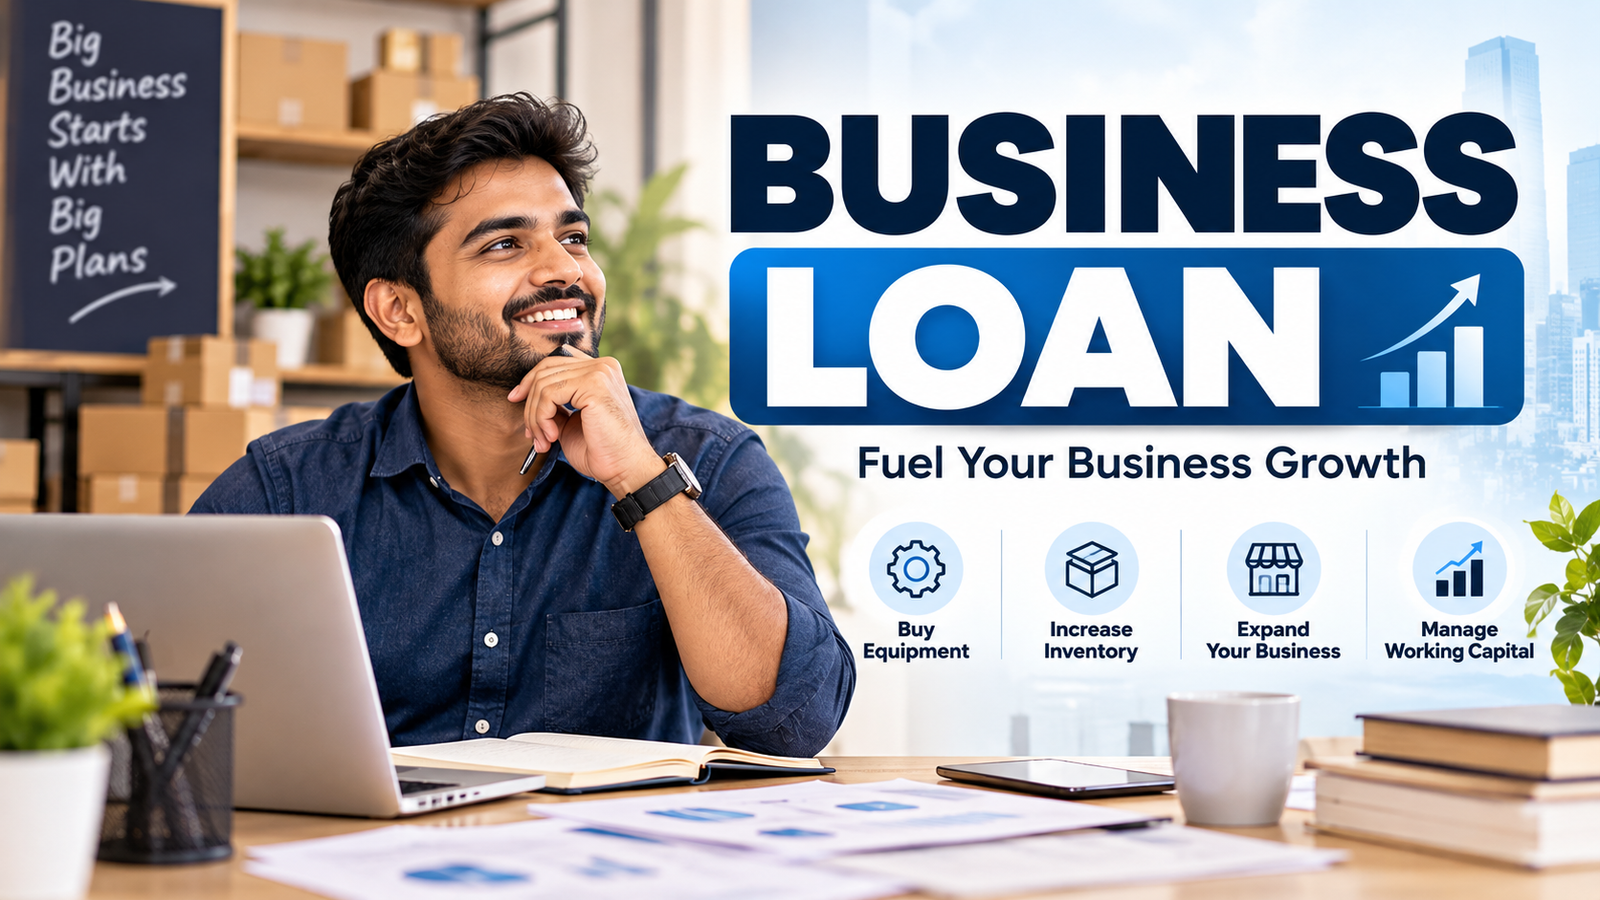
Running a business is not always easy. Sometimes, you need extra money to purchase new equipment, manage daily expenses, increase stock, hire employees, or expand your business to a new location.
Even when your business is doing well, a shortage of funds can slow down your plans. This is where a business loan can help.
A business loan gives you access to funds that you can use for eligible business needs. However, before applying, it is important to understand the eligibility criteria, required documents, interest rates, and repayment terms.
In this guide, we will explain everything you need to know about business loans in India in simple language.
What Is a Business Loan?
A business loan is a type of financing that helps business owners manage expenses or grow their businesses.
Depending on the lender and loan product, you may be able to use the funds for purposes such as:
- Purchasing machinery or equipment
- Buying stock and raw materials
- Managing day-to-day business expenses
- Opening a new branch or office
- Expanding your existing business
- Managing temporary cash flow problems
- Investing in business development
Business loans are available to eligible small businesses, medium-sized businesses, self-employed individuals, and other business entities, depending on the lender’s policies.
Who Can Apply for a Business Loan?
Business loan eligibility depends on the lender, the type of business, its financial performance, and the applicant’s credit profile.
Generally, the following applicants may be eligible:
- Small business owners
- Shopkeepers and traders
- Manufacturers and wholesalers
- Service providers
- Self-employed professionals
- Proprietors and partnership firms
- Eligible private limited companies and other business entities
The lender may also consider how long the business has been operating, its turnover, existing financial commitments, and repayment capacity.
Meeting the basic criteria does not guarantee loan approval. The final decision rests with the lender.
Business Loan Eligibility Criteria in India
Before applying for a business loan, check whether your business meets the lender’s requirements.
1. Business Vintage
Many lenders prefer businesses that have been operating for a certain period. The required duration varies depending on the loan product and lender.
If your business is relatively new, ask about financing options specifically designed for new businesses.
2. Business Turnover
Your business income helps the lender understand its financial position and ability to repay the loan.
Bank statements, financial statements, and income tax returns may be used to assess your business’s financial performance.
3. Credit Score
Your credit history can influence your eligibility, the interest rate offered, and the amount you may qualify for.
A good credit profile can help strengthen your application. Before applying, check your credit report for errors and review any outstanding payments.
4. Repayment Capacity
Lenders assess whether your business can comfortably manage the proposed EMI along with its existing expenses and loan repayments.
It is always better to choose a loan amount that matches your actual financial requirements.
5. Business Registration
Depending on the type of business and lender, you may need documents such as business registration proof, GST registration, or other applicable licences.
Requirements vary, so confirm the document list before submitting your application.
Documents Required for a Business Loan
The documents required depend on the lender, business structure, and loan amount.
Commonly requested documents include:
- PAN card of the applicant or business, as applicable
- Aadhaar card or another accepted identity document
- Address proof
- Business registration proof
- Bank statements for the required period
- Income tax returns
- Financial statements, where applicable
- GST returns, where applicable
- Photographs or additional documents, if requested
Keep your documents updated and make sure the information matches across your application and supporting records.
Submitting complete and accurate documents can help avoid unnecessary delays.
How Much Business Loan Can You Get?
The amount you can borrow depends on several factors, including your business turnover, income, credit profile, existing liabilities, and repayment capacity.
Some lenders offer smaller loans for working capital, while others provide larger amounts for business expansion or equipment purchases.
Instead of applying for the highest possible amount, calculate how much funding your business actually needs.
For example, if you need funds to purchase inventory worth ₹5 lakh, consider your expected sales, profit margins, and monthly cash flow before deciding on the loan amount.
Remember that the final eligible amount depends on the lender’s assessment.
What Is the Interest Rate on a Business Loan?
Business loan interest rates vary between lenders and loan products.
The rate offered to you may depend on:
- Your credit score and repayment history
- Business turnover and profitability
- Loan amount and repayment tenure
- Existing financial obligations
- Whether the loan is secured or unsecured
- The lender’s internal eligibility criteria
Before accepting an offer, compare the interest rate, processing fee, repayment schedule, and other applicable charges.
A loan with a lower advertised interest rate is not always the cheapest option once all fees are considered.
Secured vs Unsecured Business Loans
Business loans generally fall into two broad categories.
Secured Business Loan
A secured business loan requires collateral, such as eligible property or another accepted asset.
Depending on the lender’s terms, collateral may help an applicant access different loan amounts or repayment options. However, the pledged asset may be at risk if the borrower fails to repay.
Unsecured Business Loan
An unsecured business loan does not generally require collateral.
Instead, the lender may place greater emphasis on the applicant’s credit history, business performance, bank statements, and repayment capacity.
Not every business will qualify for an unsecured loan, and the terms may differ from those of secured financing.
Choose the option that suits your business needs and financial situation.
How to Apply for a Business Loan Through Perfect Loan
Looking for a business loan can feel confusing when different lenders offer different terms and eligibility requirements.
Perfect Loan can help you explore suitable financing options based on your requirements.
Here is how you can get started:
Step 1: Understand your funding needs
Decide why you need the loan and estimate the amount required.
Step 2: Check your eligibility
Review your business details, income, credit profile, and existing financial commitments.
Step 3: Keep your documents ready
Prepare the identity, address, business, and financial documents that may be required.
Step 4: Submit your enquiry
Contact Perfect Loan and share your basic requirements so the available options can be reviewed.
Step 5: Review the loan offer
Before proceeding, carefully check the interest rate, fees, tenure, EMI, and other terms offered by the lender.
Step 6: Complete the lender’s process
If you choose to proceed, the lender will review your application and make the final approval decision.
Loan availability, eligibility, and approval depend on the relevant lender’s policies.
Tips to Improve Your Business Loan Eligibility
A little preparation can make the application process smoother.
Here are a few practical steps to consider:
- Pay your existing EMIs and credit card bills on time.
- Maintain clear and accurate business financial records.
- Keep your bank statements organised.
- Avoid applying for multiple loans unnecessarily within a short period.
- Check your credit report and correct any genuine errors.
- Choose a loan amount that matches your repayment capacity.
- Keep business registration and tax-related documents updated.
- Compare offers from different lenders before making a decision.
These steps may strengthen your application, although they cannot guarantee approval.
Frequently Asked Questions About Business Loans
1. Can a small business owner apply for a business loan?
Yes. Small business owners may apply for business loans, provided they meet the lender’s eligibility criteria.
2. Can I get a business loan without collateral?
Some lenders offer unsecured business loans. Approval depends on factors such as business performance, credit history, and repayment capacity.
3. Is GST registration compulsory for a business loan?
Not in every case. The requirement depends on the lender, loan product, business structure, and applicable rules.
4. Does a low credit score affect business loan approval?
A low credit score may reduce your chances of approval or affect the terms offered. However, lenders may consider other factors as well.
5. How long does it take to get a business loan?
Processing time varies by lender, loan type, document completeness, and verification requirements. Ask the lender for an estimated timeline before applying.
6. Can I use a business loan for working capital?
Many business loans are designed to support working capital needs, but the permitted use depends on the specific loan product and lender’s terms.
Final Thoughts
A business loan can be useful when you need funds to manage expenses, purchase equipment, or expand your business. The important thing is to understand your requirements before borrowing.
Check your eligibility, prepare your documents, compare the available offers, and make sure the repayment amount fits your budget.
If you are exploring financing options for your business, Perfect Loan can help you understand the next steps and explore available options based on your requirements.
Make an informed decision today and plan your business’s next stage of growth with confidence.
Disclaimer: Loan eligibility, interest rates, fees, tenure, and approval are determined by the respective lender. Terms and conditions apply.